Contents
Key points
- One festive party a year, open to all employees, is not a benefit in kind (BOSS).
- Gifts and gift vouchers exempt up to €200 per employee in 2026, plus €200 per child for Christmas (URSSAF).
- The employer remains liable: limit alcohol, organise transport home.
Formats
| Format | Suited to | Idea in Provence |
|---|---|---|
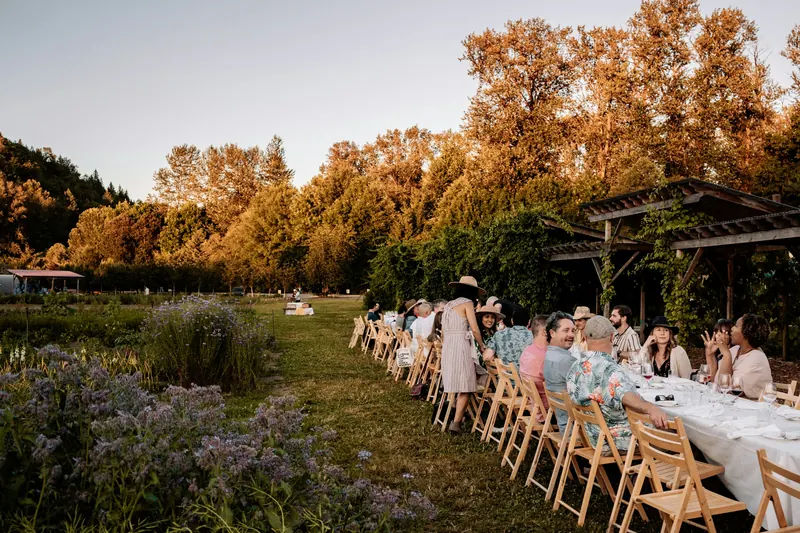
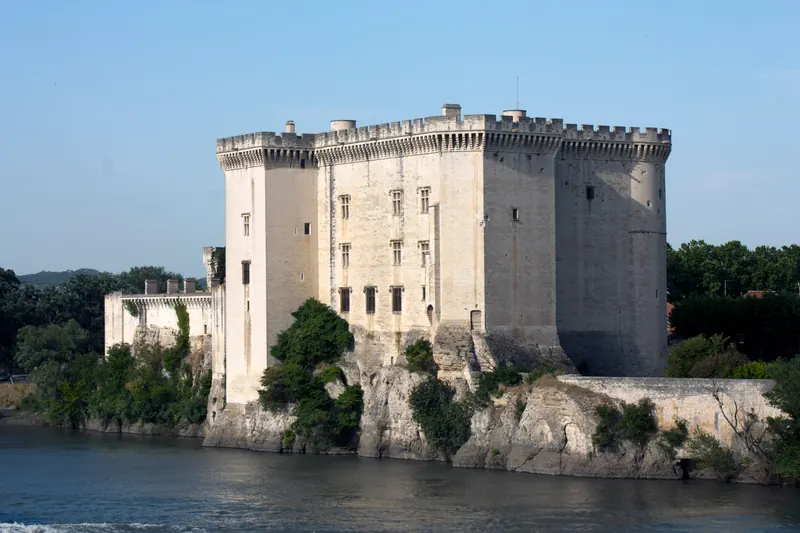
| Seated dinner | Small and medium-sized teams | In a mas or a wine estate. See château |
| Standing buffet | Large numbers, mixing teams | A rooftop or a venue with a view in Marseille |
| Themed party | All sizes | Guinguette, casino, 1980s, Provençal evening |
| Party and activity | Teams who want to get moving | Cooking workshop, tasting, then dinner. See wine tasting |
| End-of-year stay | Leadership team, small team | A night in a boutique hotel. See conference hotels |
Timeline
- September–October: set the date and the budget, book the venue.
- November: entertainment, caterer, invitations, transport.
- December: final numbers, dietary requirements, plan B.
Gifts and contributions: what URSSAF and BOSS say
These are French rules. URSSAF is the body that collects social security contributions; BOSS is the official French social security bulletin.
- The party: “no benefit in kind is to be recorded when the CSE or the employer […] organises, at most once a year, an end-of-year or company anniversary celebration, if all employees are invited and the cost of the event is global and not individualised” (BOSS). The CSE is the staff works council.
- Gifts and gift vouchers: exempt when their total value per employee per calendar year does not exceed 5% of the monthly social security ceiling (plafond mensuel de la Sécurité sociale), i.e. €200 in 2026 (monthly ceiling of €4,005). For Christmas, the threshold applies to the employee and to each child up to the age of 16 inclusive (URSSAF).
These rules are provided for information only. Have your plans checked by your chartered accountant or your HR department.
Alcohol and the employer’s liability
At the workplace, only wine, beer, cider and perry are permitted (article R4228-20 of the French labour code, the Code du travail). Off the premises, INRS, the French national institute for occupational health and safety, points out that an invited employee remains under the employer’s authority and that the employer may be held liable. Good practice: non-alcoholic drinks, food, and organised transport home. Details: company party.
Describe your party, choosing “Company party”: we pass it on to suitable venues.
Sources and method
Information checked on 11 November 2026.
- Frais professionnels — BOSS : annual festive event
- Les prestations du CSE exonérées sous conditions — URSSAF : threshold for gifts and gift vouchers, Christmas
- Plafonds de la Sécurité sociale — URSSAF : 2026 monthly ceiling
- Article R4228-20 du Code du travail — Légifrance : drinks permitted
- Fêtes d’entreprise et consommation d’alcool — INRS : recommendations
Frequently asked questions
Are Christmas gifts to employees subject to social security contributions in France?
According to URSSAF, the French body that collects social security contributions, gifts and gift vouchers are exempt when their total value per employee per calendar year does not exceed 5% of the monthly social security ceiling, i.e. €200 in 2026. For Christmas, this threshold applies per employee and per child up to the age of 16 inclusive.
Is the end-of-year party a benefit in kind?
No, according to BOSS, the official French social security bulletin, provided the employer or the CSE (the staff works council) organises it at most once a year, all employees are invited and its cost is global rather than individualised.
When should you book the venue for the end-of-year party?
As early as possible: Fridays and Saturdays in December are snapped up quickly. A weekday evening, or a New Year event in January, leaves more choice.